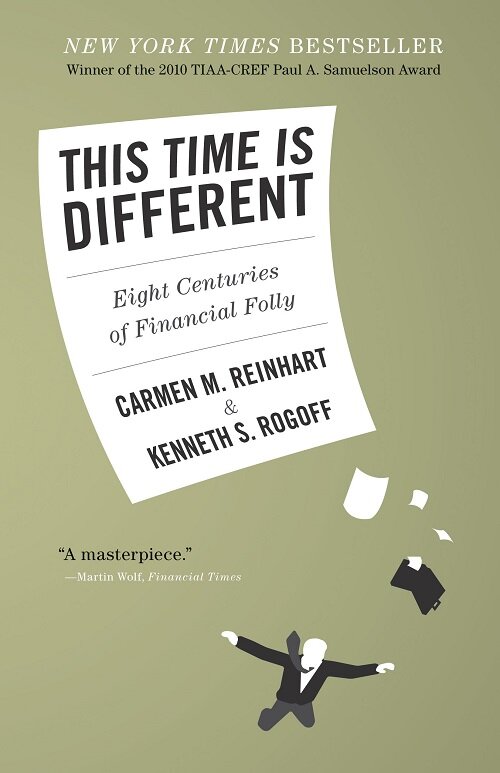
This Time Is Different: 8 Centuries of Financial Folly
At a Glance
A useful history of how debt turns growth stories into financial fragility.
7/10
Book
This Time Is Different: Eight Centuries of Financial Folly
Authors
Carmen M. Reinhart & Kenneth S. Rogoff
Original publication
Princeton University Press, 2009
Edition read
Korean translation (Dareunsesang, 2010), 501 pages
Read
December 2023
Updated
October 27, 2026
Read it if
You want to understand how debt becomes dangerous and why financial crises recur, even when each boom seems different.
Skip it if
You expect precise trading signals or a light read. The historical comparisons and extensive statistics take patience.
Why I Picked It Up
By late 2023, I was finding markets difficult to make sense of.
The previous year, rising interest rates and falling stock and crypto prices had seemed to mark the end of a speculative boom. Yet stocks were approaching their earlier highs again. Rates remained elevated, and inflation had not quietly disappeared.
There had also been serious banking trouble. Silicon Valley Bank was closed in March, while Credit Suisse, already weakened by a loss of confidence and outflows, ended up in a rescue takeover by UBS. Their problems differed, but their distress made the financial system look less secure than the recovery in share prices suggested.
Markets soon had reasons to look ahead. Investors expected the Fed to respond to financial stress. ChatGPT had also helped turn AI into a powerful growth story, bringing big technology companies back to the center of the rally.
I did not need convincing that AI mattered. What puzzled me was how much that promise could justify: higher valuations, larger investments, and more borrowing. Previous booms had surely come with persuasive explanations of their own. I wanted to understand what those explanations had overlooked.
What It’s About
Carmen Reinhart and Kenneth Rogoff compare sovereign defaults, banking crises, inflation, and currency crises across centuries. Three ideas stayed with me.
Excessive borrowing usually comes with a plausible explanation. Sometimes the reassurance is strong growth and high savings. Sometimes it is better institutions, sophisticated financial products, or more capable policymakers. The changes may be real. The mistake is assuming they also guarantee the borrower’s ability to repay.
The terms of the debt matter alongside its size. Buying property with short-term borrowing can work while lenders keep renewing the loans. If they stop, a valuable asset may still have to be sold cheaply because cash is needed immediately. Foreign-currency borrowing introduces another vulnerability: a weaker domestic currency makes repayment more expensive. Looking only at external debt can also miss vulnerabilities in domestic borrowing.
A banking crisis can become a government debt problem. Credit tightens, spending weakens, and tax receipts fall while fiscal pressures rise. Bailouts alone therefore do not explain the increase in public debt. The book finds that real government debt rose by an average of about 86% in the three years after major postwar banking crises. That is a sample average, not a forecast for every country.
What Works: Following the Borrowing Behind the Boom
The book moves beyond explanations based on greed or poor judgment. By putting capital inflows, lending, asset prices, and the aftermath together, it helps explain why a situation could look sound before becoming fragile.
Rising asset prices increase collateral values. That collateral supports more borrowing, which can push prices higher again. When prices fall, the same process works in reverse: collateral weakens, credit tightens, and sales to repay debt put further pressure on prices.
This also changes how I think about a promising technology. Its potential and the financing needed to reach that potential have to be examined together. A good long-term idea can still be supported by borrowing terms that leave little room for disappointment. After reading the book, I became more interested in those terms alongside the price increases themselves.
What Remains Difficult: History Does Not Supply a Timetable
The limitation is the distance between recognizing a familiar vulnerability and knowing what will happen next.
Countries differ in their institutions, policy options, creditors, and borrowing currencies. Heavy debt can persist for years. Expensive assets can become more expensive, and policy support can extend a boom beyond what seems reasonable. Identifying a bubble does not by itself make betting against it straightforward.
The authors acknowledge the limits of early warnings. Conditions can become more conducive to crisis without revealing the date of a break or the size of the eventual damage. Applying the historical comparisons still requires judgment about both the recurring features and the differences that might change the outcome.
October 2026 Update
What AI Data Centers Bring to Mind
AI infrastructure financing makes these questions concrete. A company commits money to facilities and equipment before recovering that investment through the sale of computing capacity. Strong demand does not remove the need to finance that gap.
Reuters reported on October 15 that CoreWeave’s five-year credit default swap spread had exceeded 1,100 basis points. The yield on its bonds due in 2031 briefly reached 16% before retreating to around 14%. A CDS transfers credit risk; a higher spread means buying that protection has become more expensive.
A traded bond yield is not the rate on every new loan. Even so, higher underlying rates and a larger credit-risk premium can make borrowing and refinancing more demanding. Capacity must earn enough, for long enough, to cover equipment, construction, and interest. Customers may keep arriving while margins shrink if financing costs rise or rental prices disappoint.
Contract duration matters too. A $2.6 billion loan CoreWeave announced in August had a term of roughly five years, while the customer contracts supporting it averaged about three years. The company described renewals or re-leasing capacity as ways to extend the revenue stream.
The earlier short-term borrowing example concerns renewing debt. Here, the question is whether revenue can continue after customer contracts expire while the loan is still outstanding. The average does not mean every contract ends before the loan matures.
The loan itself shows that financing had not simply disappeared. Still, believing in AI’s growth and believing a particular borrower can repay comfortably require separate judgments.
My review of Power and Progress takes up the question that remains even if the investment succeeds: who shares in the gains.
U.S. Debt: The Cost of Keeping Borrowing in Place
Governments face refinancing questions too. At the end of 2023, when I read the book, gross U.S. federal debt was about $34.00 trillion. By October 22, 2026, it was about $40.44 trillion, an increase of roughly $6.44 trillion. Gross debt includes intragovernmental holdings. (U.S. Treasury debt data)
Journey in Garret / Debt and financial risk
U.S. federal debt
Monthly observations · January 2019–October 22, 2026
Gross federal debtDebt held by the public
Hover, tap, or use ← → to inspect each observation.
Observation dateOct 22, 2026
Gross federal debt$40.4443 tn
Held by the public$32.5977 tn
Gross debt includes intragovernmental holdings. Debt held by the public includes Federal Reserve holdings. Each month uses its last available observation; October 2026 is partial, through October 22.View the data table
During Janet Yellen’s tenure as Treasury secretary, bills outstanding increased from about $3.64 trillion in September 2022 to $6.00 trillion in September 2024. Their share of marketable Treasury debt rose from 15.4% to 21.7%. Rebuilding the government’s cash balance after the 2023 debt-limit impasse contributed to that increase. (2024 FSOC report)
By September 2026, under the Trump administration, bills had reached about $7.12 trillion, or 22.4% of marketable debt. Short maturities require frequent issuance, exposing borrowing costs more quickly to changes in market rates. The denominator here is marketable Treasury securities, not gross federal debt. (Treasury debt composition)
Journey in Garret / Debt and financial risk
More debt comes due soon
Treasury bills / marketable Treasury securities · each September
Hover, tap, or use ← → to inspect each observation.
Observation dateSep 30, 2026
Bills / marketable debt22.36%
Bills outstanding$7.1181 tn
September 30 observations. The denominator is total marketable Treasury securities, not gross federal debt. Treasury bills have original maturities of one year or less.View the data table
Federal net interest outlays increased from about $475 billion in fiscal 2022 to approximately $1.052 trillion in fiscal 2026. These are complete fiscal-year budget figures, distinct from gross interest expense. (Monthly Treasury Statement)
Journey in Garret / Debt and financial risk
The cost to the federal budget
Net interest outlays · fiscal years 2022–2026
Hover, tap, or use ← → to inspect each observation.
Observation dateSep 30, 2026
Net interest outlays$1,051.75 bn
Fiscal year2026
Full fiscal-year net interest outlays. The U.S. fiscal year runs from October through September. This budget measure is distinct from gross interest paid on federal debt.View the data table
The dollar’s reserve-currency role and deep Treasury market support U.S. financing. They do not make rising debt costless. Higher yields feed into government interest spending through new borrowing and refinancing, while also influencing corporate funding conditions. (IMF U.S. report, Congressional Budget Office)
France: Fiscal Confidence Within a Shared Currency
France shows why the currency and policy framework matter. Fiscal concerns, political uncertainty, and protests coincided with a sharp repricing of its debt. Reuters reported that the French ten-year yield spread over Germany reached 177.7 basis points intraday on October 22, the widest since November 2011. That comparison concerns the spread, not France’s outright borrowing rate.
France cannot independently determine euro-area monetary policy or central-bank support. Yet the ECB does have conditional bond-purchase tools. Euro-denominated French debt should therefore not be equated with foreign-currency borrowing by a country whose own currency can depreciate against the debt. Fiscal credibility and the conditions of the shared safety net both matter. (ECB’s Transmission Protection Instrument)
Journey in Garret / Debt and financial risk
France’s borrowing premium
France minus Germany · long-term government bond yields
Separate intraday report · October 22, 2026
177.7 bp
Widest since November 2011, according to Reuters. This daily-market observation is separate from the monthly line.
France − Germany
Hover, tap, or use ← → to inspect each observation.
Monthly averageSep 2026
France − Germany96.7 bp
France yield4.440%
ECB convergence-rate series for representative government bonds with approximately ten years to maturity. Spread = (France yield − Germany yield) × 100. One basis point = 0.01 percentage point. The monthly line ends in September 2026; it does not include the October 22 intraday report.View the data table
The monthly-average series ends in September 2026 at 96.7 basis points. The October 22 intraday report is a separate observation, not another monthly average. One basis point equals 0.01 percentage point. (ECB long-term interest-rate statistics)
Korea: Looking Beyond Government Debt
On comparable 2025 estimates in the IMF’s April 2026 Fiscal Monitor, Korea’s government-debt-to-GDP ratio is lower than those of the United States and France. Household borrowing nevertheless needs separate attention. (IMF Fiscal Monitor)
Household credit reached KRW 2,019.8 trillion at the end of the second quarter of 2026, up KRW 25.9 trillion from the previous quarter. Meanwhile, the Financial Services Commission’s April 2026 release put the year-end household-debt-to-GDP ratio at 98.7% in 2021 and an estimated 88.6% in 2025. A growing nominal balance and a declining GDP ratio can coexist. The two series also differ in coverage and observation date. (Bank of Korea, Financial Services Commission)
Journey in Garret / Debt and financial risk
Korea: the balance and the ratio
Year-end household debt / GDP · 2017–2025
Separate statistic · household credit, June 30, 2026
KRW 2,019.8 trillion
Up KRW 25.9 trillion from the previous quarter. Bank of Korea household credit includes household loans and merchandise credit.
Household debt / GDP
Hover, tap, or use ← → to inspect each observation.
Observation dateDec 31, 2025 · est.
Household debt / GDP88.6%
Source statusEstimated
Ratio series: FSC release of April 1, 2026, using one source vintage. The 2025 ratio is an estimate in that release and is shown with a hollow point and dashed final segment. The nominal household-credit callout is a separate BOK statistic, with different coverage and date; it is not plotted on the GDP-ratio axis.View the data table
In 1997, government finances alone could not reveal the risks building in corporate and financial institutions’ short-term foreign borrowing. Today’s won-denominated household loans have a different currency and refinancing structure. The relevant concern now is how income, housing prices, and interest costs affect borrowers’ ability to repay. (IMF’s 1998 assessment)
Tail Risk: When Pressures Arrive Together
Losses can become much larger when shocks reinforce one another. Three conditional paths are worth considering:
The United States and AI companies: A jump in Treasury yields could increase both government interest spending and corporate refinancing costs. Weak data-center renewals could then trigger asset sales that depress collateral values and restrict further borrowing.
France: Political deadlock and weak growth could compound fiscal pressure. Falling bond prices and higher funding costs could spread losses into financial institutions and weaken private lending.
Korea: Falling incomes and house prices could increase household arrears while nonbank property losses tighten credit. Weaker consumption, tax receipts, and any financial support could then shift part of the burden to public finances.
These are transmission mechanisms, not predictions of an imminent crisis. What matters is whether financing continues and whether repayment pressure spreads into forced sales and shrinking credit.
Read Next
Narrative Economics, Robert J. Shiller: Examines how persuasive stories spread and influence economic behavior, complementing the borrowing examined here.
The Most Important Thing, Howard Marks: Connects an awareness of cycles and financial vulnerability with price, risk, and investor behavior.
Final Thought
What stayed with me was what happens after the money has been borrowed. When will the cash to repay it arrive? If debt falls due first, can it be refinanced? Who absorbs the loss if that cash flow breaks down?
AI investment, French government bonds, and Korean household debt lead back to those questions, despite their different structures. I would recommend This Time Is Different to readers who want to investigate them through financial history. It gave me a reason to examine debt and repayment terms more closely whenever the outlook sounds especially convincing.
[…] This Time Is Different by Carmen Reinhart and Kenneth Rogoff: eight centuries of evidence that financial crises keep returning in the same shape. […]
Leave a Reply